Overseas · Guide
Roshan Digital Account for property: how it works
By Pakizzle Editorial Team · Checked against official sources on
Published · Updated on · 11 min read

The short answer
Overseas Pakistanis can buy property in Pakistan through a Roshan Digital Account (RDA) in two ways: pay from their own RDA balance (self-investment) or take Roshan Apna Ghar home finance from their RDA bank. Register the purchase with the bank before paying, pay the seller directly from the RDA rupee account, and keep records for repatriation.
Key facts
| Fact | Value | Source | As of |
|---|---|---|---|
| SBP said at the 2021 launch of Roshan Apna Ghar that when the property is sold, the principal invested can be remitted abroad without needing any permission. | Principal repatriable | Dawn | |
| Roshan Digital Accounts reached 975,602 with cumulative inflows of USD 14.157 billion by end-September 2026, per SBP data. | 975,602 accounts; USD 14.157bn (Sep 2026) | APP: RDA inflows rise to $14.157 bn in Sep 2026 (SBP data, 14 Oct 2026) | |
| For a non-resident buyer holding POC, NICOP or CNIC who buys through an FCVA or NRVA, the 236K advance tax is the final tax for the buyer. | 236K final (1.25% for ATL buyers) | FBR: Income Tax Ordinance 2001, amended up to 30 June 2026 | |
| Meezan Bank's Roshan Apna Ghar finances up to 85% of property value for purchase or plot plus construction, for 3 to 25 years. | Up to 85%; 3-25 years | Meezan Bank: Roshan Apna Ghar FAQs | |
| If property bought from an RDA is sold early, Meezan says you can repatriate up to the lower of sale proceeds or principal; the rest only after three years. | 3-year rule on gains | Meezan Bank: Roshan Apna Ghar (matches SBP's RDA FAQ) | |
| SBP says Roshan Digital Accounts come in two types: a Foreign Currency Value Account (FCVA) and an NRP Rupee Value Account (NRVA). | FCVA and NRVA | State Bank of Pakistan: FAQs on Roshan Digital Account |
For overseas Pakistanis, the hardest part of buying property back home is often the money: how to send it, how to pay the seller safely, and how to get it out again later. The Roshan Digital Account (RDA) was built for this. This guide explains the two ways to use it for property, the tax treatment as of November 2026, and the steps in order.
SBP's Roshan Apna Ghar page sets the framework: non-resident Pakistanis and POC holders can borrow for 3 to 25 years, at 1-year KIBOR (lien-based) or KIBOR + 1.5% (non-lien-based) on variable rates, or at the 5-year PIB PKRV rate (plus 1.5% if non-lien-based) fixed for five years, with free property insurance up to the financed amount. SBP sets no maximum financing share, minimum loan or fee; those are bank terms, so the figures below from the banks' published terms differ between banks.
Quick facts
- RDA launched on 10 September 2020 with commercial banks. It lets non-resident Pakistanis open a bank account in Pakistan online, without visiting a branch.
- By end-September 2026 there were 975,602 accounts and cumulative inflows of USD 14.157 billion, according to State Bank of Pakistan data reported by APP.
- Allied Bank says any Pakistani citizen aged 18 or over living abroad can open one, as can POC (Pakistan Origin Card) holders, and residents who have declared foreign assets in their latest wealth statement.
- Roshan Apna Ghar is the RDA product for property. SBP said in 2021 that account holders could "buy or finance a house from bank's pre-approved projects or any other property".
- In March 2026 the government decided to open RDA to foreign nationals, foreign companies and institutional investors, for government securities and Naya Pakistan Certificates. The report did not say whether this extends to property.
Two ways to use RDA for property
1. Self-investment from your own balance
You pay for the property from money already in your RDA. Meezan Bank's terms set out the rules clearly:
- Register the purchase with the bank before paying the seller anything.
- Make all payments from your RDA rupee (PKR) account, so the proceeds can be repatriated later.
- Payments go directly to the seller only.
Meezan describes self-investment as covering any residential or commercial property in Pakistan, "on a repatriable basis".
2. Roshan Apna Ghar home finance
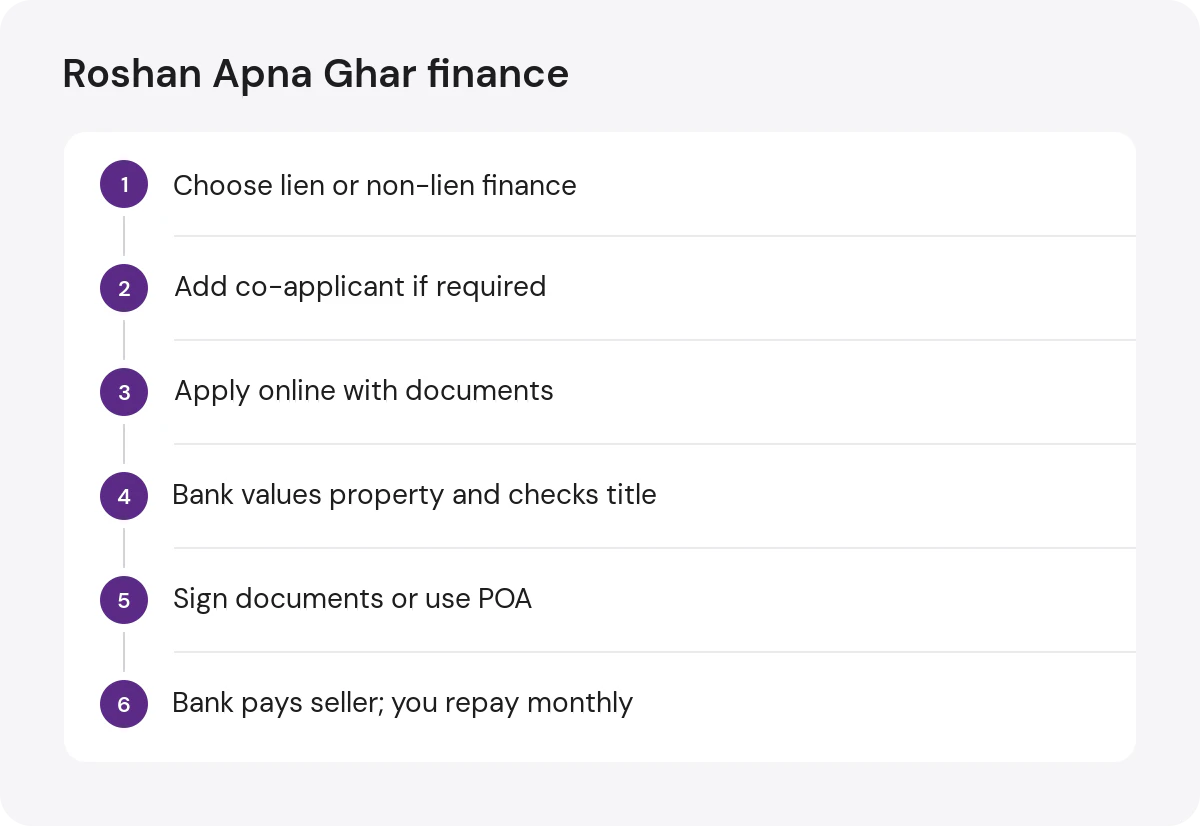
Bank financing for RDA holders; terms differ by bank.
Your RDA bank lends part of the price. Products are offered in conventional and Islamic forms. Meezan's version, for example, works on diminishing musharakah (joint ownership that you buy out over time).
| Term | Meezan Bank (as of November 2026) | | --- | --- | | Uses | Home purchase, plot plus construction, construction, renovation | | Minimum finance | PKR 5 lakh | | Maximum finance | Up to 85% of property value (30% for renovation) | | Tenure | 3 to 25 years | | Pricing | Linked to 1-year KIBOR or 5-year PKRV, plus a margin for non-lien finance | | Age | 20 to 65 years | | Processing fee | PKR 4,000 plus FED | | Early settlement | 1% in the first year, none after that |
There are two types. Lien-based finance is secured against money you keep in your RDA. Meezan says it does not need you in Pakistan, and a co-applicant is optional. Non-lien finance needs your physical presence or a power of attorney to sign the title papers, and a co-applicant, at least one of whom lives permanently in Pakistan. Allied Bank says its Roshan Apna Ghar needs a co-applicant who is an immediate family member living in Pakistan.
Other banks set their own limits and rates. Compare at least two before you apply.
Tax when you buy and sell
These are the rules in FBR's consolidated Income Tax Ordinance, amended up to 30 June 2026.
| Stage | Tax | Treatment for RDA holders | | --- | --- | --- | | Buying | 236K advance tax, 1.25% of fair market value from July 2026 | Final tax for the buyer if you are a non-resident POC, NICOP or CNIC holder paying through an FCVA or NRVA | | Selling | 236C advance tax, 2.75% of the sale price from July 2026 | Final tax instead of capital gains tax, if you bought through an FCVA or NRVA | | Either | Higher non-filer rates | Do not apply to non-resident POC or NICOP holders on 236C and 236K transactions (Second Schedule, clause 111AC) |
In plain words: as a non-resident buying through these accounts, you pay the filer rate even if you are not on the Active Taxpayers List, and the advance tax closes your income tax on that purchase or sale. This matches SBP's 2021 description of the RDA property tax regime as "simple and final". The tax law speaks of FCVA and NRVA accounts rather than naming the RDA, but SBP's RDA FAQs say "There are two types of accounts offered under Roshan Digital Accounts": a Foreign Currency Value Account (FCVA) and an NRP Rupee Value Account (NRVA). Keep the bank's statement showing the payment went from your RDA, because the registrar or society will need it.
Provincial taxes, such as stamp duty, registration fee and CVT, and the society's transfer fee are separate and still apply. See our explainer on 236C advance tax.
Steps for a self-investment purchase
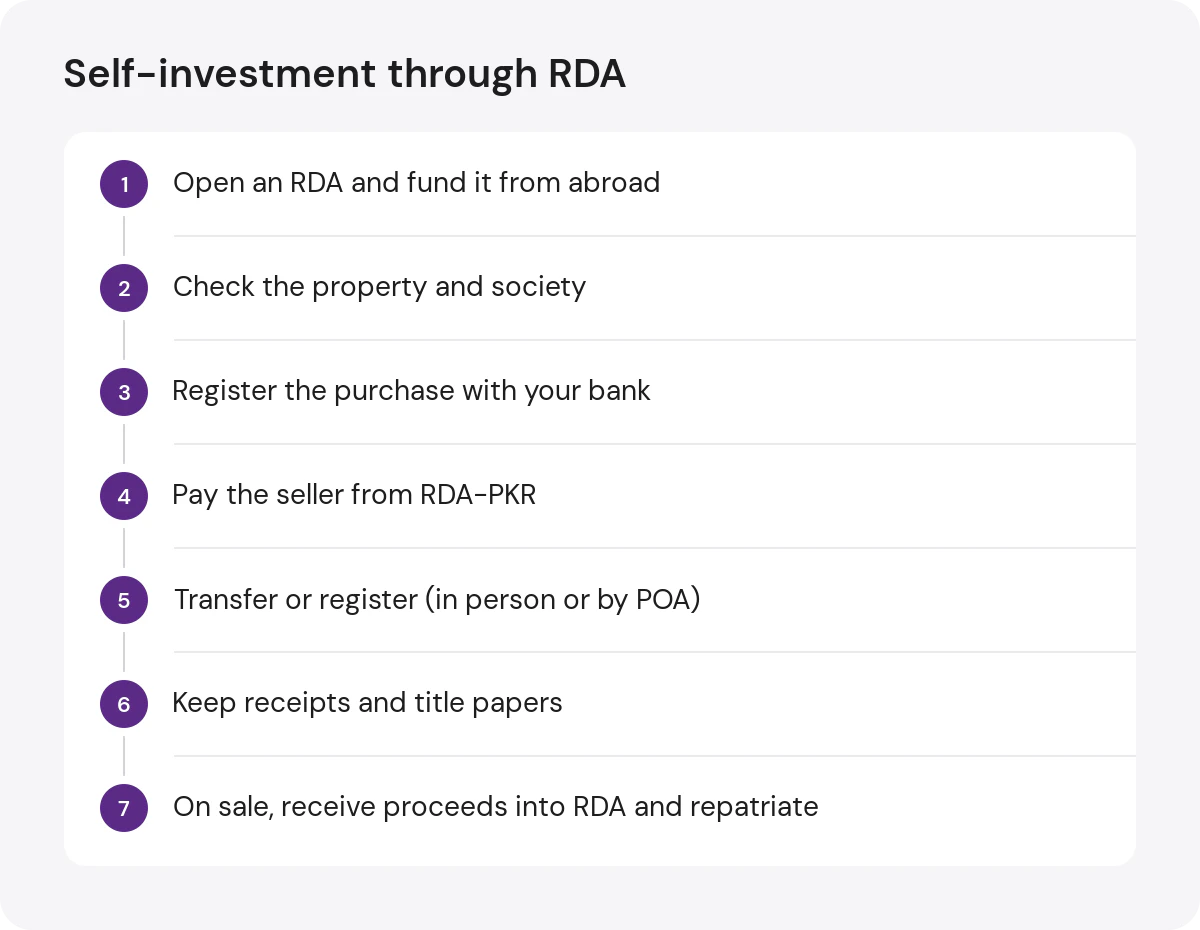
Register with the bank first, pay the seller directly, keep the trail for repatriation.
- Open and fund your RDA. Apply online through your chosen bank with your CNIC, NICOP, POC or passport, proof of non-resident status, and proof of income. Allied Bank says the application takes 15 to 20 minutes.
- Check the property. Confirm the seller's ownership and the society's approval before you commit. Our guide on how to check if a housing society is approved explains how.
- Register the purchase with your bank. Do this before paying any token (bayana, the advance payment).
- Pay the seller from your RDA-PKR account. Pay directly to the seller's account, never to a dealer or a third person.
- Complete the transfer or registry. Attend yourself, or appoint an attorney through a power of attorney. See our guide on power of attorney for property.
- Keep the paper trail. Keep bank confirmations, the sale agreement, tax challans and the transfer letter or registry. You will need them to repatriate money when you sell.
Documents you will usually need
- CNIC, NICOP or POC, and passport with entry and exit stamps
- Proof of non-resident status, such as a visa, residence permit or iqama
- Proof of income, such as a job letter or salary slips
- For finance: the bank's application form, property documents and, for non-lien finance, a power of attorney and co-applicant documents
- The seller's ownership documents and the society's NDC (No Demand Certificate)
Repatriation: what to expect
SBP said at launch that "in case of sale of property, the principal amount invested can be remitted abroad without needing any permission". Banks apply conditions, though. Meezan says that if you sell early you can repatriate up to the lower of the sale proceeds or your original investment in PKR, and the remaining difference and profit only after three years. SBP's RDA FAQ sets the same rule: if you disinvest from real estate within three years, "the principal amount invested can be repatriated at any time while the capital gain, if any, can be repatriated after three years from the date of investment". For instalment purchases, the date of the last instalment counts.
Delays happen. In a 2024 letter to Dawn, a reader wrote that his son sold a DHA Lahore plot bought through RDA, and more than a month later the bank had still not approved sending the money abroad. Ask your bank for its repatriation process in writing before you buy, and make sure the buyer pays into your RDA.
Red flags
- A dealer asks you to send money to his account "to save time" instead of paying the seller from your RDA.
- You are told to pay before the bank has registered your purchase.
- The project is described as "bank approved" but your bank has no record of it.
- The seller's name on the bank account differs from the owner's name on the title.
- Pressure to buy from photos alone, with no video viewing or independent visit.
If something goes wrong
If a payment goes to the wrong person, contact your bank at once and ask it to try to recall the transfer, then file a police complaint. If repatriation is delayed, write to your bank's complaints unit, keep a reference number, and if it is not resolved, escalate to the State Bank of Pakistan or the Banking Mohtasib. SBP's Roshan Apna Ghar page names [email protected] for RDA queries.
For a large purchase or a financing decision, speak to your bank and a tax adviser in both countries before you commit.
How Pakizzle helps
Pakizzle's Overseas mode shows prices in your currency, and many listings offer video viewing, so you can shortlist from abroad. Look for listings with dated checks such as "Documents checked" and "Video checked", sellers with an ID verified blue tick, and phone numbers verified by call-back. These help you shortlist; they are not a guarantee of title. Our area price pages help you judge whether an asking price is fair, and the token money checklist covers what to confirm before you pay anything. To estimate the federal taxes, use our 236K calculator when you buy and the 236C calculator when you sell.
Questions
Can I buy any property with my Roshan Digital Account?
When SBP launched Roshan Apna Ghar in 2021 it said account holders could buy or finance a house from a bank's pre-approved projects or any other property. Meezan Bank's self-investment terms mention any residential or commercial property in Pakistan. Your bank still checks the property and the seller, and you should check the society's approval yourself.
Do I need to come to Pakistan to buy property through RDA?
Not always. For self-investment you pay from the account online. For transfer or registration, you either attend or give a power of attorney to someone you trust. Meezan says lien-based finance does not need physical presence, but non-lien finance needs you present or a power of attorney to sign title documents.
Roshan Apna Ghar ke liye co-applicant zaroori hai?
It depends on the bank and the product. Allied Bank says its Roshan Apna Ghar needs a co-applicant who is an immediate family member living in Pakistan. Meezan says a co-applicant is optional for lien-based finance but mandatory for non-lien finance, with at least one living permanently in Pakistan.
What tax do I pay when I buy through RDA?
As a non-resident POC or NICOP holder you pay the filer rate even if you are not on the Active Taxpayers List, under clause 111AC of the Second Schedule. Advance tax under 236K (1.25% from July 2026) is final for the buyer if you pay through an FCVA or NRVA. Provincial stamp duty and registration fees still apply.
How do I send the money back after I sell?
Make sure the sale price is paid into your RDA, then ask your bank to repatriate it. SBP's RDA FAQ says the principal can be repatriated at any time, while any capital gain can be repatriated three years after the investment. Banks apply their own conditions, and delays have been reported, so ask your bank for its written repatriation rules before you buy.
Sources
- Dawn: Roshan Apna Ghar scheme for overseas Pakistanis soon (26 Aug 2021)
- The News: Foreign firms, nationals allowed to open Roshan Digital Accounts (17 Mar 2026)
- Meezan Bank: Roshan Apna Ghar
- Meezan Bank: Roshan Apna Ghar FAQs (PDF)
- Allied Bank: Roshan Digital Account Pakistan
- FBR: Income Tax Ordinance 2001, amended up to 30 June 2026 (s.236C, s.236K, Second Schedule clause 111AC)
- FBR: Circular No. 02 of 2026-27, Finance Act 2026 explained (8 Sep 2026)
- Dawn: Repatriation of funds, letter to the editor (13 Sep 2024)
- State Bank of Pakistan: Roshan Apna Ghar
- State Bank of Pakistan: FAQs on Roshan Digital Account
- APP: RDA inflows rise to $14.157 bn in Sep 2026 (SBP data, 14 Oct 2026)
Corrections
- : We updated the Roshan Digital Account figures to end-September 2026: 975,602 accounts and USD 14.157 billion in cumulative inflows (State Bank of Pakistan data, reported by APP on 14 October 2026). We had given end-February 2026 figures from The News.
Tools for this
Related guides
- Overseas Pakistanis Foundation (OPF) housing schemes Overseas
OPF, the government's Overseas Pakistanis Foundation, runs housing schemes in Islamabad, Lahore, Gujrat, Peshawar, Dadu, Larkana and Mirpur…
- Checking an agent remotely: a checklist Overseas
To check a property agent from abroad, verify their CNIC, office and FBR DNFBP registration, call past overseas clients, and insist on a…
- Renting out your property in Pakistan while abroad Overseas
To rent out property in Pakistan while abroad, appoint one trusted manager with a special power of attorney limited to renting, check the…
- Selling inherited property from abroad Overseas
To sell inherited property from abroad, first transfer it to all the legal heirs through a NADRA succession certificate, letter of…